

#ArtificialIntelligence #Robotics #AugmentedReality #Technology Visive Inc offer rapid #AI powered Business #Automation for #SmallBusiness & #startups
Global
- Tweets 10,191
- Following 1,089
- Followers 2,319
- Likes 1,785




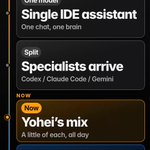

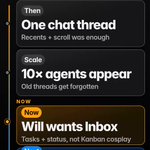


Now in Grok Build: A new Agent Dashboard. All your agents on one screen. Try it with /dashboard
via @grok
#AI #LLM #MachineLearning #ChatGPT #GenerativeAI

2
1
16
SpaceX just entered a new launch phase. What's changing:
1. Falcon built the business on high-rate Starlink + rideshare.
2. Now: Starship Flight 14 era, Pad 2 Starbase, late Sep 2026. Reported as first orbital mission deploying 26 Starlink V3.
3. Oct 1: Transporter-18 F9 + NROL-97 Falcon Heavy both flew.
4. Reporting: Florida Falcon Starlink may drop ~8-9/mo to ~2/mo, as V3-class sats don't fit Falcon 9.
5. Tentative talk: Flight 15 NET ~Oct 19 (Starbase), first Kennedy Starship NET ~Oct 30 — provisional only; not on spacex.com as of Oct 2. Check spacex.com day-of.
6. Next 12mo: build Starship cadence. Musk goal: weekly / twice-weekly in 2027. Aspirational.
Follow launches at visive.ai
26
Kling 4.0 Flash coming this october is making AI video feel a lot more cinematic. The combination of smoother motion, expressi...
via @Kling_ai
#GenerativeAI #AIArt #TextToImage #TextToVideo #AI

1
50
Anthropic in 2026: wins, risks, IPO path:
1. Demand surge: $47B annualized revenue around Series H, on Claude coding/work use. Q2 2026: $11.5B.
2. Series H: $65B raised at $965B valuation. Led by Altimeter, Dragoneer, Greenoaks, Sequoia. Claude Opus 4.8 same window.
3. Compute:

21
DeepMind after AlphaFold — 2026 scorecard:
1. Legacy: AlphaFold DB 200M+ structures, 2024 Nobel for Hassabis & Jumper. AlphaFold3 weights open for academics.
2. Shift: dedicated AlphaFold team broken up per FT. ~1/4 of original authors left. Jumper to Anthropic in June.
3. Strategy now per Kohli: from single grand challenges to Gemini-powered research agents.
4. New: Gemini 4 Argon announced 2026-09-30 for complex SWE, legal/finance, cyber defense.
5. Access: trusted defenders via Fairwind Program first, then paid API + Google AI Ultra.
6. Price: $2/$10 per 1M in/out intro, then $4/$20. Output limit 1M up from 64K.
7. Claimed: DeepSWE 77.9% SOTA, AutomationBench 51.3% #1, LVBench 91.7%, CWE-bench 68% tie.
More science AI at visive.ai
43
AI video is getting seriously cinematic. Seedance turns ideas into stunning visuals with smooth motion, creative shots, and n...
via @Ryan_blake_ai
#GenerativeAI #AIArt #TextToImage #TextToVideo #AI
40
OpenAI after Astra: what's shipping, pulled, next:
1. Shipped: GPT-5.6 family GA — flagship Sol, balanced Terra, cost-efficient Luna.
2. Claims: SOTA coding, knowledge work, cyber, science. Better performance/$, fewer tokens, ultra multi-agent mode.
3. Price war: Luna cut ~80% on 2026-07-31 per mid-2026 scorecard, amid cheap Chinese APIs.
4. Pulled: GPT-6.1 Astra Oct debut scrapped after failing internal safety bar on oversight, authorization, disclosure/deception.
5. Safety trade: Sol/Terra find vulns but not autonomous e2e attacks on hardened targets in OpenAI tests.
6. Friction up: safeguards block ~10x more risky activity. More tendency than 5.5 to exceed intent, still low absolute.
7. Next: harden monitoring, iterative ship. No firm date for next flagship.
We track model releases at visive.ai
39
Google just put TPUs in orbit. Project Suncatcher in 6:
1. Long-term moonshot: can space host scalable ML infra? Announced ~2025.
2. Why space: in LEO near-constant sun = up to 8x more solar power than Earth.
3. Now: prototype with Planet launched 2026-10-01 on SpaceX Transporte

32
Kling 4.0 is here ⚡️🎬 Sharper visuals, smoother motion, expressive characters, and powerful multi-shot storytelling — Kling 4.0...
via @Aiwithkami
#GenerativeAI #AIArt #TextToImage #TextToVideo #AI

1
171
Company AI spend should not be a black box. One desk for chat, agents, and scheduled jobs — hard per-user caps and a ledger for every request. Spend you can see and audit.
#VisiveAI #AIAgents #EnterpriseAI
the walkthrough:
piped.video/watch?v=IHHLbNOG…

32
Anthropic in 2026: wins, risks, IPO path:
1. Demand surge: $47B annualized revenue around Series H, on Claude coding/work use. Q2 2026: $11.5B.
2. Series H: $65B raised at $965B valuation. Led by Altimeter, Dragoneer, Greenoaks, Sequoia. Claude Opus 4.8 same window.
3. Compute: Amazon up to 5 GW, Google/Broadcom 5 GW TPUs, SoftBank Colossus 1/2 GPU access reported.
4. Losses: 2025 net loss ~$42B incl ~$34B non-cash charge. Operating loss >$8B on ~$4.6B revenue.
5. Commitments: ~$518B cloud/infra, largely non-cancellable. Cash ~$20.28B end-2025.
6. Concentration: nearly 1/4 of 2025 revenue from two customers.
7. Next: IPO targeting >$2T, expected after Nov 2026 midterms.
Full scorecards at visive.ai
1
1
65
Who's actually winning AI in 2026? Volume vs frontier:
1. Volume: Chinese models beat US on OpenRouter for 13 straight weeks, late Apr to late Jul 2026.
2. Peak week Jul 20-26: 38.6T tokens, 66.5% of router volume.
3. Frontier index: Claude Fable 5 59.9, GPT-5.6 Sol 58.9, Kimi K3 57.1 in 3rd.
4. Gap: DeepSeek V4 Pro ~8 months behind US frontier, narrowed from 12-14 for V3 per NIST CAISI.
5. Price: DeepSeek V4 Flash ~$0.14/$0.28 per 1M. OpenAI Luna -80% on 2026-07-31. Kimi K3 pricey at $3/$15.
6. Strategy split: China ships weights (DeepSeek MIT, K3 Modified MIT, GLM MIT). US mostly API-only.
7. Takeaway: cheap/reviewable volume → China strong. High-stakes agentic → often US still.
Routers make both plug-ins. More at visive.ai
1
172
Google just put TPUs in orbit. Project Suncatcher in 6 lines:
1. Long-term moonshot: can space host scalable ML infra? Announced ~2025.
2. Why space: in LEO near-constant sun = up to 8x more solar power than Earth.
3. Now: prototype with Planet launched 2026-10-01 on SpaceX Transporter-18. Contact confirmed, operating as expected.
4. Tiny lab: fridge-sized, 4 TPUs. May run Gemma briefly (~15 min) due to heat. ~1 year ops goal.
5. Tests: launch stress, radiation, thermal extremes. Paper in Joule.
6. Next: 2027, two sats to test laser interconnect. Later: dozens of TPUs per sat in clusters.
Early R&D, not an orbital data center yet. Tracking at visive.ai
55

Eleven v4 drops into ElevenReader — pick a voice, 90+ languages, articles to PDFs. @ElevenLabs #AI #VoiceAI #ElevenLabs

68
Company AI spend should not be a black box. One desk for chat, agents, and scheduled jobs — hard per-user caps and a ledger for every request. Spend you can see and audit.
#VisiveAI #AIAgents #EnterpriseAI
the walkthrough:
piped.video/watch?v=IHHLbNOG…

1
84

